14:20POPlt 1841 words
Brightline Florida Parents File Chapter 11 to Restructure $2.5 Billion
Seventeen Brightline Florida parent companies filed Chapter 11 in New Jersey with $2.5 billion in debt; Assured Guaranty and bondholders committed $490 million in new financing.
· 4 min journey
Calling at
- Seventeen Brightline Florida parent companies filed Chapter 11 on Sept. 24 in U.S. Bankruptcy Court for the District of New Jersey, carrying about $2.5 billion of the group's $7.1 billion in funded debt.
- Assured Guaranty and mutual fund bondholders committed $490 million in new long-term financing under a restructuring support agreement; the operating company did not file and trains continue running.
- Roughly $4.4 billion in operating-company and affiliate bonds, including those securing the Tampa and commuter rail rights, remain in place with no principal reduction, while $1.12 billion in 11% Brightline East notes held by Davis Polk-represented noteholders sit outside the deal.
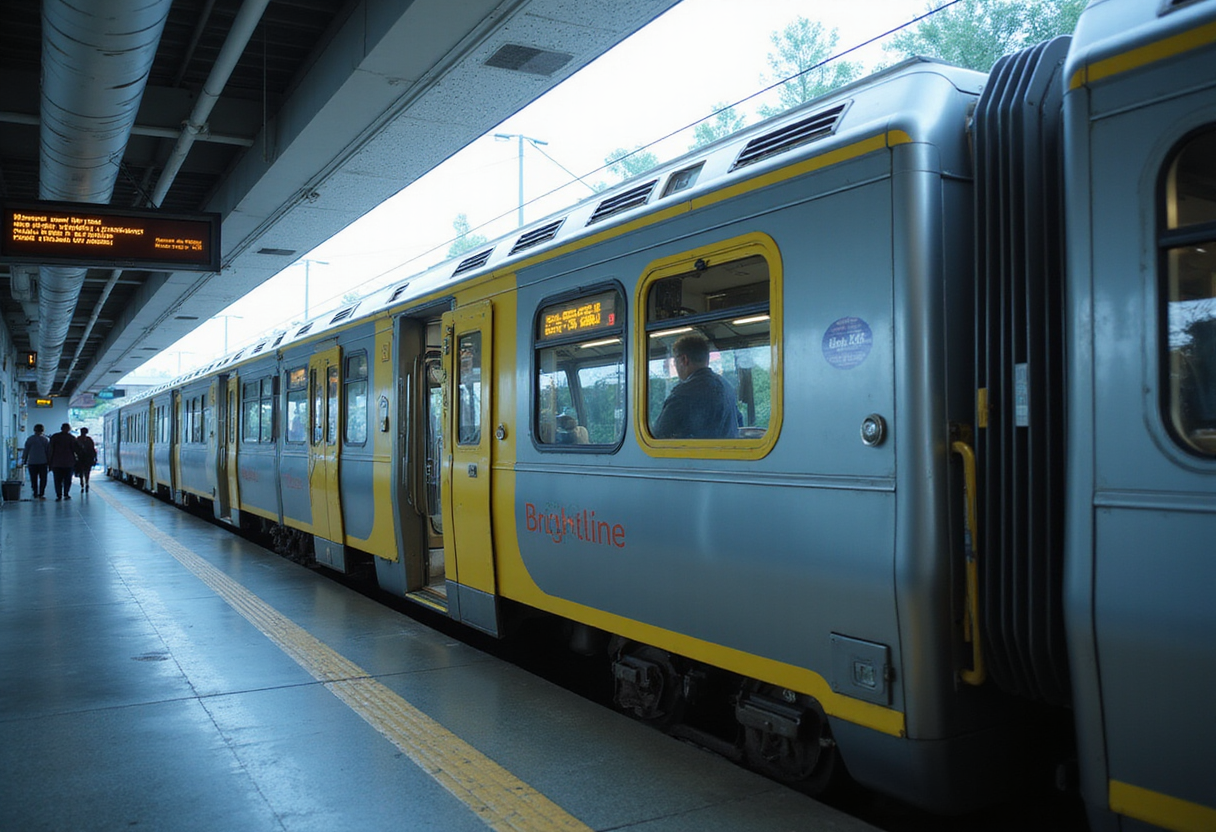
Seventeen parent companies of Brightline Florida filed for Chapter 11 bankruptcy on Sept. 24 in U.S. Bankruptcy Court for the District of New Jersey, carrying roughly $2.5 billion in holding-company debt. Brightline Trains Florida, the entity that owns and operates the Miami-to-Orlando service, did not file, and the company says trains will continue running as normal.
The prearranged filing follows a restructuring support agreement with bond insurer Assured Guaranty and a group of mutual fund bondholders, who committed $490 million in new long-term financing to be funded when Brightline emerges from bankruptcy. Brightline says the agreement will significantly deleverage its balance sheet and improve liquidity. Court filings do not yet detail how each class of debt will be treated.
About $4.4 billion in bonds issued for the operating company and the affiliates holding Brightline's commuter and Tampa rights will remain in place during the restructuring with no reduction in principal, according to Brightline. Total funded debt across the parent companies, operating company and affiliates stands at approximately $7.1 billion, according to a sworn declaration by Brightline Florida CEO Patrick Goddard.
The filing comes despite operational momentum: year-to-date ridership and revenue through August are up 14%. The restructuring is nonetheless necessary, Goddard's declaration states, because ridership and fares fell short of the projections the company borrowed against. He cited the COVID-19 service suspension from March 2020 to November 2021, slower-than-expected growth in third-party booking channels, marketing cuts in 2025, and delays from litigation.
Two rounds of outreach to new investors — contacting 32 parties in the first round and 64 in the second, the latter also seeking buyers for company assets — produced no deal.
Goddard frames the case as a balance-sheet fix. "Brightline is a critical part of Florida's transportation network that has changed the way people move around the state. [This] agreement brings $490 million in new long-term capital to Brightline from the stakeholders who know this business, and it comes at a time of real momentum," he said. "This transaction will be a catalyst for further growth in ridership and revenue."
Brightline Train Development LLC CEO Nicolas Petrovic echoed that the restructuring "is not expected to impact operations. It will give Brightline the balance sheet to match the growth we're already seeing across the business."
Holdout noteholders
Noteholders of Brightline East's $1.12 billion in 11% senior secured notes — represented by Davis Polk & Wardwell and the largest single debt owed by the filing companies — are outside the agreement. Brightline defaulted on those notes, according to the declaration, when it expanded its short-term bridge financing in June without the noteholders' consent. Brightline says it will continue working to build consensus with additional stakeholders.
The company asked the court for permission to continue paying wages and benefits, a standard Chapter 11 request. Roughly 520 Brightline employees work for Brightline Management LLC, one of the debtors, rather than the operating company.
Growth rights as collateral
Federal agencies have pledged funding to multiple Brightline projects, including a $57.5 million award to Cocoa, Fla., for a new station Brightline would run and a $78.9 million grant to Stuart, Fla., to replace the St. Lucie River rail bridge, a project estimated at $262 million. Brightline has committed $26.2 million toward the local match, according to its court filing.
Brightline's rights to extend service to Tampa and develop South Florida commuter rail sit with affiliates outside the bankruptcy — but both sets of rights are pledged as collateral for bonds that have gone months without interest payments. On July 15, 2026, the affiliate holding the Tampa extension rights missed a third straight interest payment on $1.2 billion in bonds; the first two were deferrals allowed under the bond terms.
Brightline West, the separate Las Vegas–Southern California high-speed project, is not part of the filing, though one debtor holds a roughly 40% stake in it.
A deteriorating timeline
The bankruptcy follows a string of missed payments. A $775 million parent-company loan missed an interest payment on July 15, 2025, and a required 10% principal payment on Aug. 8. That loan matured unpaid on Nov. 8, 2025. On Aug. 13, Brightline rolled $985 million in bonds tied to its South Florida commuter rail rights — which it was required to buy back — into new bonds at 10% interest. An interest payment on those commuter rail bonds went unpaid on Feb. 15, 2026, with bondholders extending the grace period multiple times. Assured Guaranty lent the operating company $22.2 million on May 21, 2026, to cover short-term needs; the bridge loans later grew to $148.9 million, issued at 70 cents on the dollar.
A first-day hearing is scheduled for Sept. 29 in bankruptcy court, where Brightline will seek interim approval of its bankruptcy financing and permission to keep paying employees, with a final financing hearing to follow. The company has requested that its full financial schedules come due Nov. 9.
via gobrightline.com (Original)
More from James Calloway
Show full bio
Correspondent covering consumer brands and retail at Mainline Report.
150 articles
Connecting services · Related articles
- 14:20
Brightline Secures $490m in Restructuring to Deleverage Florida Operations
- 15:50
Brightline Florida Files for Bankruptcy; Las Vegas Rail Delayed
- 15:40
Brightline Florida Files Bankruptcy, Raising Questions Over West Coast Plans
- 08:23
Brightline to File for Bankruptcy After Multiple Deaths: Reports
- 18:53
Brightline Bankruptcy Puts US Private Passenger Rail Financing on Trial